
Clive Palmer's promise to cap mortgage rates at 3% would make it much harder to get a home loan
- Written by: Isaac Gross, Lecturer in Economics, Monash University
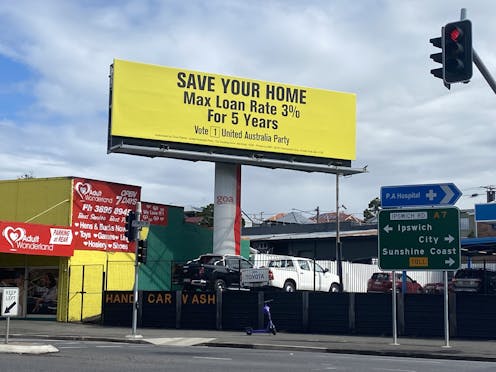
Clive Palmer’s United Australia Party continues to make waves in the federal election campaign, most recently with advertisements on massive billboards pledging a “maximum 3% interest rate on all home loans for five years”. But does this promise stack up?
Keeping mortgage rates at their record lows for five years is a bold promise. Especially because – as Clive Palmer well knows – the government doesn’t set interest rates.
The key driver is the Reserve Bank of Australia, which sets the cash rate to keep inflation at a low and stable level of 2-3%. But once the cash rate is set, every other bank is entitled to lend money out at whatever competitive rate they want. They frequently diverge from the cash rate based on their cost of obtaining funding from Australian savers and from overseas.
On its website[1], the United Australia Party (UAP) says it would “use the power of the Constitution to put a cap on the bank home lending rate at a maximum of 3% for the next five years.” (It also promises to introduce a 15% export licence for all iron ore exports from Australia, and “pledge the proceeds from such licences to be used for the retirement of the one trillion-dollar debt mountain that Australia faces”.)
For a moment, let’s run with this 3% idea from the UAP. Imagine for a minute it held the balance of power or even had a majority in both houses of parliament.
If UAP really did intend to try and deliver on an election promise to cap interest rates at 3% for five years, what would the flow-on effects be?
Read more: 5 interview questions for the next RBA deputy governor[2]
Mortgages just for the wealthiest
The government did control interest rates for many years, until deregulation in the Hawke years. Government control of interest rates and the banking sector made home loans very hard to get, forcing Australians to set up inefficient building societies and credit unions to skirt around the regulations.
But, say the UAP passed a law saying you can’t lift interest rates above 3% – no matter what. You will soon run into problems.
The first is that if banks can’t make a profit on mortgages – if, for example, it costs 4% to borrow and they can only charge 3% – then lending doesn’t make financial sense for them. The banks will just stop writing mortgages entirely.
Even if they can squeak a small profit margin they may only write mortgages for the wealthiest and safest Australians to lend to. Wealthy households are less likely to default and thus are cheaper for banks to lend to.
In other words, a 3% cap on interest rates would lead to a situation where either banks stop mortgages entirely or greatly restrict them. A lot of would-be home owners will not be able to get a mortgage at all.
And if you can’t get a mortgage at all, then for most of us it doesn’t matter what the rate is because you can’t buy a house in the first place. If lending dried up, the number of house buyers would plummet, which would devalue homes.
The only thing worse than a banking system that is expensive is one that is in crisis and potentially getting bailed out or going bankrupt, which might very well imperil the financial stability of the banking sector and derail the economy.
OK, how else could they ensure a 3% interest rate for people?
Apart from changing the law, another way to deliver on this commitment is by hugely increasing government spending.
Perhaps the government could pay home owners the difference between whatever their interest rate is and the promised 3%. So, say your interest rate was 4%. That’s 1% more than the promised 3%, so the government could pay that 1% difference for you, using taxpayer money.
Of course, that would be incredibly costly. Australia’s household debt is almost twice its income. Paying even a small share of the interest payments would be an enormous burden on the budget.
It would be, in effect, a subsidy for all mortgage owners; a hugely expensive giveaway to the richest people in Australia.
Read more: Few restrictions, no spending limit, and almost no oversight: welcome to political advertising in Australia[3]
Alright then, what if we just changed the RBA’s job description?
There is a third way you could cap interest rates at 3% and that is to rewrite the RBA’s mandate and ban them from lifting the cash rate for five years.
But the reason the RBA pushes up interest rates is to help control inflation and the cost of living. That’s why there’s talk of an interest rate rise[4] after inflation hit a whopping 5.1% this week.
Banning the RBA from pushing up rates comes with real inflationary risks. That would overheat the economy and drive up inflation. You’d see hugely higher prices at the supermarket and the fuel pump.
Perhaps you think homeowners are more deserving than renters or pensioners or anyone in the economy who doesn’t have a mortgage. But I don’t.
No free lunch
In a recent podcast interview[5] with Michelle Grattan, independent MP Andrew Wilkie mentioned this UAP ad, saying:
In my opinion, this is the worst campaign I’ve observed, as far as the mud slinging and the dishonesty. There used to be some limits on the dishonesty of the political parties and the candidates but there seem to be no limits this election. There’s a billboard down the road from Clive Palmer’s United Australia Party, promising a 3% maximum mortgage rate. I mean, they know that’s just nonsense.
Whatever your view, it’s worth remembering there is no such thing as a free lunch in the economy. If you want to make something cheaper, you have to pay for it some other way.
You either have to pay for it from taxpayers’ money or you make the banks pay, which comes with a real risk of financial crisis.
Read more: Game of Loans: Australia's Reserve Bank loses its heir apparent[6]
References
- ^ website (www.unitedaustraliaparty.org.au)
- ^ 5 interview questions for the next RBA deputy governor (theconversation.com)
- ^ Few restrictions, no spending limit, and almost no oversight: welcome to political advertising in Australia (theconversation.com)
- ^ talk of an interest rate rise (theconversation.com)
- ^ interview (theconversation.com)
- ^ Game of Loans: Australia's Reserve Bank loses its heir apparent (theconversation.com)
Authors: Isaac Gross, Lecturer in Economics, Monash University