
Negative equity is looming for some home owners – but you only need to worry if you need to sell
- Written by: Stephen Hickson, Economics Lecturer and Director Business Taught Masters Programme, University of Canterbury
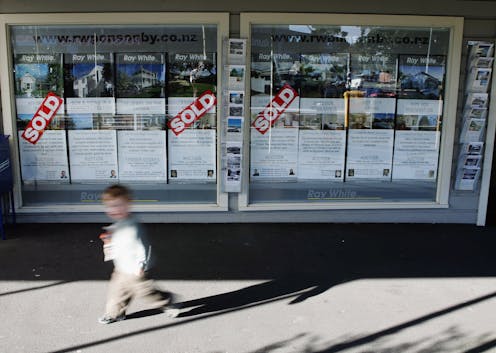
It feels like a perfect storm is building. The rising cost of living and higher interest rates are putting household budgets under stress, and falling house prices could push some home owners into negative equity.
On the one hand, the drop in house prices is a good thing as it makes housing more affordable, particularly for young people – and we want that.
But every transaction has two sides. Dropping house prices are bad for those who need or want to sell their house, or who hold most of their wealth in their home. These people are now markedly poorer.
In September 2017, the average house in New Zealand cost NZ$666,518[1]. By January 2022, prices had peaked at $1,063,765. But by September 2022, the average house price had slipped to $956,592. The downward trend may continue for a while yet.
Some 32% of New Zealand households have a mortgage on the primary residence[2], with the median property debt increasing to $260,000 in the year ended June 2021, up $56,000 over the past three years.
A looming threat
For most home owners, a small or even moderate fall in the value of their home won’t make any practical difference. Their house will still probably be worth more now than it was two years ago and it will still be worth more than their mortgage.
However, for those whose mortgage is a high fraction of the value of their home – those who bought property in 2021 when rates were low and house prices high, for example – the risk is that they will fall into negative equity.
Read more: What happens if I can't pay my mortgage and what are my options?[3]
A borrower enters negative equity if the value of their home drops below the value of their mortgage.
For around 2% of New Zealand mortgage holders, this threat has become a reality[4].
But is it time to panic? Well, probably not. As long as you don’t need to sell your house and you can sustain your mortgage payments, then negative equity doesn’t matter all that much. You can just wait it out.
That said, negative equity can become more of an issue when other economic issues – rising inflation, unemployment or interest rates – rear their heads.
Contributing risk factors
Lets start with interest rates. Rising interest rates are making debt more expensive. Local media are already publishing stories of white collar workers struggling to pay their mortgages[5].
Yes, interest rates are rising but they are still relatively low. The floating rate for a first mortgage is currently 6.8%. Prior to the 2008 global financial crisis (GFC), this interest rate tier hit a peak of 10.9%[6].
That said, interest rates fell over the course of the GFC, while rates are currently rising. Furthermore, the level of debt held by many households is now higher since people had to take on bigger mortgages as house prices rose. Bigger debt levels makes higher interest rates harder to cope with.
Unemployment will make negative equity a bigger issue. Currently, New Zealand’s unemployment rate is historically low[7], meaning most people with a mortgage can feel relatively secure in their job or job prospects.
But it won’t stay there.
The low unemployment makes it harder for the Reserve Bank of New Zealand (RBNZ) to rein in inflation, particularly if wages continue to rise. The RBNZ has been clear that New Zealand needs to get ready for a rise in unemployment, with some economists saying 50,000 New Zealanders would need to lose their jobs to bring inflation under control[8].
Rises in both unemployment and interest rates at the same time will increase the chance that some highly-leveraged mortgage holders get into problems.
Did we learn from the GFC?
Negative equity was a big problem during the 2008 GFC as house prices fell and banks accumulated bad loans. This issue hit the United States and parts of Europe particularly hard.
But that doesn’t mean we are heading to the same place now.
Following the 2008 crisis, New Zealand’s lending rules changed, requiring banks to be more cautious when lending. In 2021, these rules were refined even further[10]. The number of low-equity loans that banks could make was reduced and banks had to look more closely at a borrower’s ability to repay debt.
Read more: Fighting inflation doesn’t directly cause unemployment – but that's still the most likely outcome[11]
Some of these requirements have certainly made it harder for first home buyers, perhaps overly so, but it has reduced the risk in our financial system.
This time around there will be fewer borrowers with mortgages that are a high fraction of the value of their house and fewer who can’t manage higher mortgage repayments.
Banks also have no incentive to push people into a default on their mortgage. This is especially true when there is negative equity. The bank doesn’t win if they force the sale of a home and get back less than they were owed. And the headline “Bank evicts mum with two toddlers” never plays well.
So expect banks to work hard with any struggling mortgage holders to help them keep paying the mortgage.
The immediate future is not going to be pleasant for many borrowers. The RBNZ must get inflation down. Doing that will not be easy and homeowners should prepare for higher interest rates.
But negative equity is not a problem providing you don’t need to sell your house and you can afford to pay your mortgage.
Even if unemployment rises to 7%, which is just above the post GFC peak, that would still mean a 93% employment rate. Most people will be in work, living in their house and paying their mortgage – even those with negative equity.
References
- ^ average house in New Zealand cost NZ$666,518 (www.qv.co.nz)
- ^ mortgage on the primary residence (www.stats.govt.nz)
- ^ What happens if I can't pay my mortgage and what are my options? (theconversation.com)
- ^ has become a reality (www.theguardian.com)
- ^ white collar workers struggling to pay their mortgages (www.stuff.co.nz)
- ^ hit a peak of 10.9% (www.rbnz.govt.nz)
- ^ unemployment rate is historically low (www.stats.govt.nz)
- ^ lose their jobs to bring inflation under control (www.stuff.co.nz)
- ^ Getty Images (www.gettyimages.com.au)
- ^ refined even further (www.consumerprotection.govt.nz)
- ^ Fighting inflation doesn’t directly cause unemployment – but that's still the most likely outcome (theconversation.com)
Authors: Stephen Hickson, Economics Lecturer and Director Business Taught Masters Programme, University of Canterbury