
inflation may already be retreating and going too hard risks a recession
- Written by: Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University
One of the stranger things about the Reserve Bank’s announcement[1] of why it’s lifting interest rates by 0.25 percentage points is that it suggests inflation will come down by itself.
“A further rise in inflation is expected in the near term,” the RBA says, “but as supply-side disruptions are resolved, inflation is expected to decline back towards the target range of 2-3%.
So why raise rates now, for the first time in more than a decade? The bank says it is about "withdrawing some of the extraordinary monetary support that was put in place to help the Australian economy during the pandemic”, which is fair enough.
But our latest burst of inflation is weird, and resistant to rate hikes. If the Reserve Bank isn’t careful, too many more rate hikes like this might help bring on a recession.
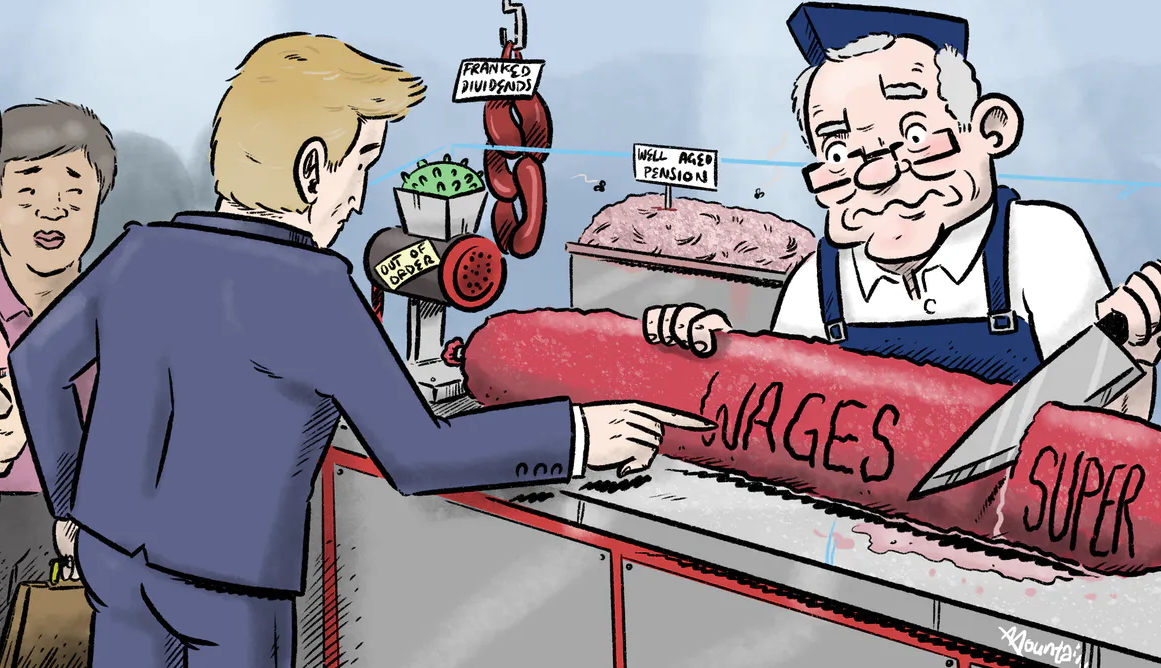
Labor’s Anthony Albanese is as good as correct when he says “everything is going up except your wages[2]” – not completely correct, because wages are going up, by a minuscule 2.3% per year on the official figures; but essentially correct, because when it comes to prices, almost every single one is going up.
Every three months the Bureau of Statistics prices around 100,000[3] goods and services. They account for almost everything we buy, the exceptions including illegal drugs and prostitution, where pricing would be “difficult and dangerous[4]”.
Read more: What's in the CPI and what does it actually measure?[5]
Among the types of bread the bureau prices are rye, sliced white, and multigrain, from all sorts of stores in every capital city. Where the bureau doesn’t price a type of loaf, it is a fair bet its price moves in line with the loaves it does price.
Then it groups these 100,000 or so prices into “expenditure classes”, 87 of them. “Bread” is one, “breakfast cereals” is another. Furniture and rent are two others.
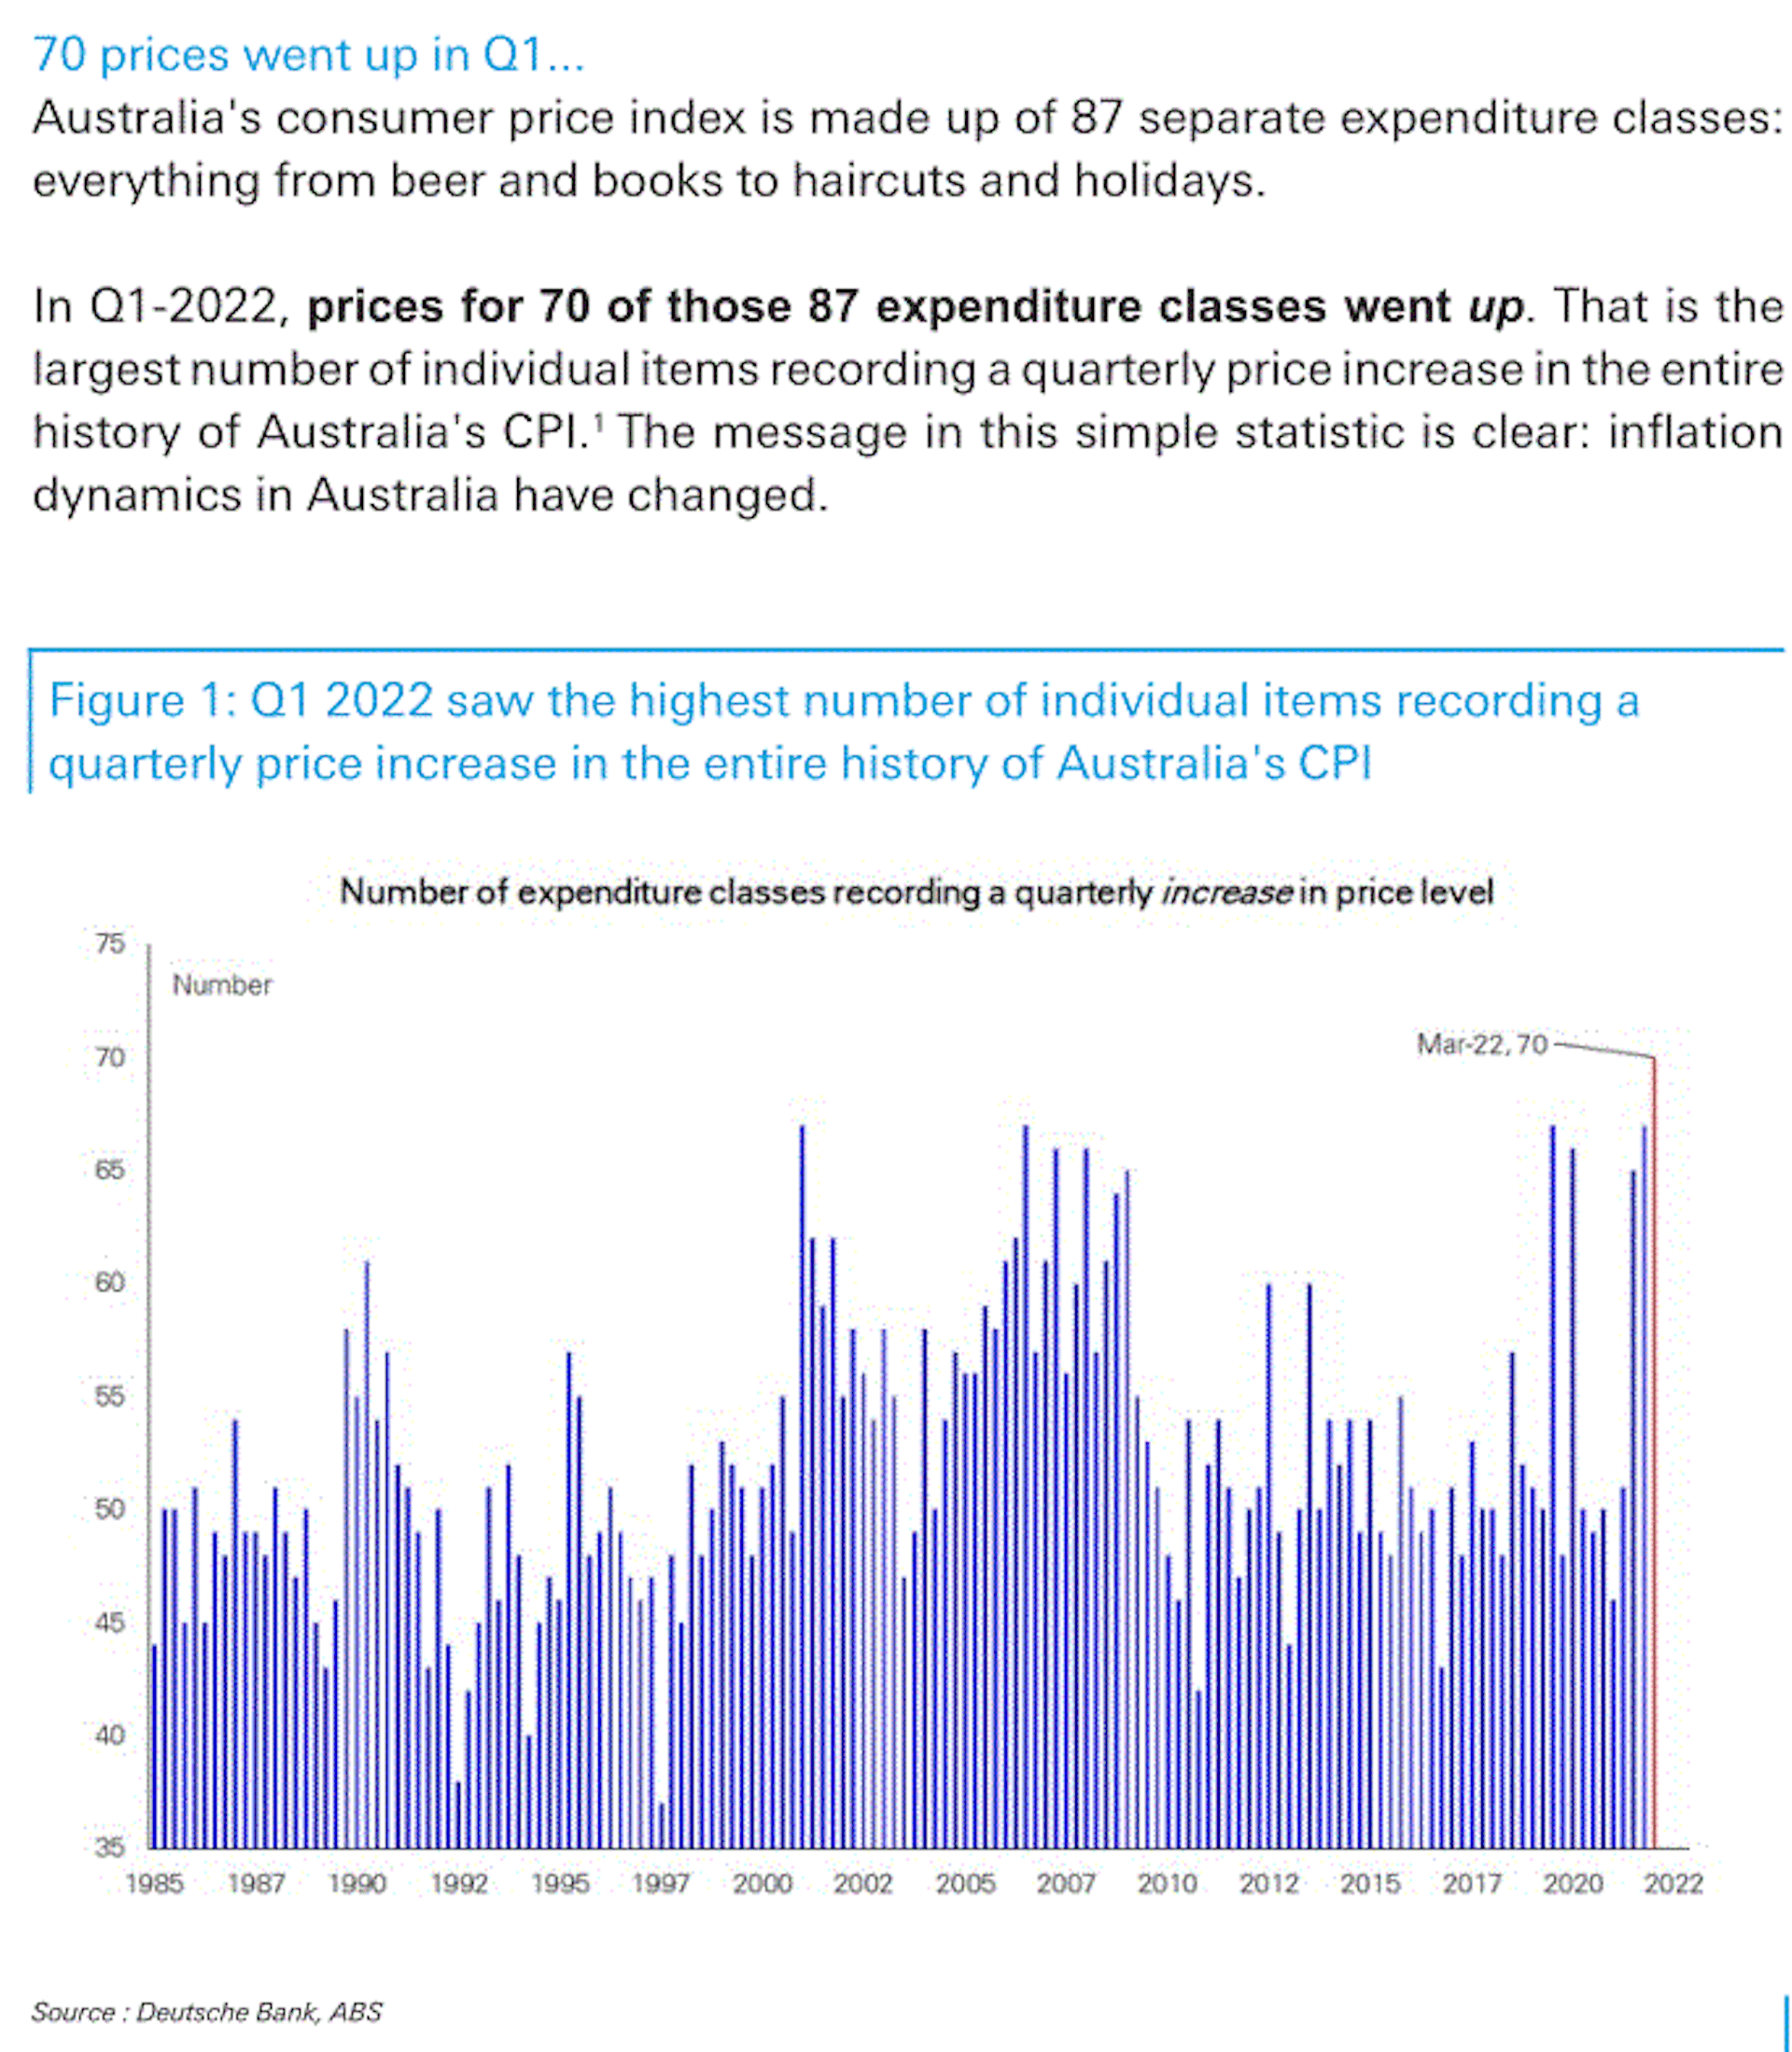
Rarely do the expenditure classes move as one. Typically, only 50 or so of the 87 climb in price. But in the March quarter just finished, an astounding 70 climbed in price; according to Deutsche Bank economist Phil O'Donaghoe, that’s the most ever in the 72-year history of the consumer price index.
And the prices that climbed most – by far – were the ones we had little choice but to pay.
Necessities up, treats not as much
The bureau divides the 87 classes of goods into “non-discretionary[6]” and “discretionary”.
It classifies bread as non-discretionary, biscuits as discretionary; petrol as non-discretionary, new cars as discretionary, and so on.
In the year to March, non-discretionary inflation (the price rises we can’t avoid) was a gargantuan 6.6%[7] – well above the official inflation rate of 5.1%, and the highest in records going back to 2006.
Discretionary inflation – the price rises on the treats we splurge on if we’ve got the money – was only 2.7%[8].
Not since 2011 has the gap been that wide, which makes this inflation unusual.
While price rises are extraordinarily widespread – because most things need diesel to move them, and we were hit with floods, COVID-linked supply problems and the invasion of Ukraine all at once – they don’t seem to be the result of splurging.
These price rises are more like a tax.
The usual response to the usual hike in inflation is to hike interest rates. It’s a way to take away access to cash and push up mortgage and other payments so people have less money to spend[9] and push up prices.
But this hike in inflation is doing that by itself, as the government recognised in the budget by handing out $250 cash payments[10] to compensate.
These price rises are like a tax
If the big price rises are beyond our control and making us poorer, hiking interest rates to make us poorer still, in the hope we will splurge less on things whose prices we can influence (and whose price rises are small) might not achieve much.
Done repeatedly, the Reserve Bank could push up interest rates because inflation is high, discover inflation is still high, push interest rates higher in response, notice inflation is still high, push interest rates even higher in response… and so on, until it had brought on a recession.
A recession is already a risk with these sorts of price rises. If big enough, they can force consumers to cut other spending to the point where the economy stagnates and creates unemployment in the face of inflation – so-called “stagflation[11]”.
Inflation might have already fallen
Another response would have been to wait. Seriously. The floods, invasion and supply problems pushing up prices in recent months are likely to pass, pushing down inflation and pushing down a lot of prices.
It might have already happened. The oil price has fallen 11% from its peak, down 2.5% in the past two weeks alone. And inflation has fallen – on one measure, to zero.
Read more: Inflation hits 5.1%. How long until mortgage rates climb?[12]
The official Bureau of Statistics measure of inflation is produced every three months, but for 13 years now the Melbourne Institute of Applied Economic and Social Research has produced its own simpler monthly measure[13], which tracks the official rate pretty well.
Although missing a lot (tracking fewer types of bread, and a national rather than a city-by-city measure) it is produced quickly and more often, providing a better insight into prices in real time.
The latest, released on Monday, points to an inflation rate of zero[14] in April.
Why rate hikes need only be mild
That’s right. While some prices continued to rise as always, enough prices fell to offset that. The high inflation in the lead-up to March stopped or paused in April.
It’s different in the United States. There, inflation is being supercharged by wage growth averaging 9%[15] and the Federal Reserve is about to lift interest rates aggressively[16].
Here, wages growth in the year to December was just 2.3%[17]. We’ll get the figures for the year to March in a fortnight. There’s a good case for future rate hikes to be a good deal less aggressive.
References
- ^ announcement (www.rba.gov.au)
- ^ everything is going up except your wages (twitter.com)
- ^ 100,000 (www.rba.gov.au)
- ^ difficult and dangerous (theconversation.com)
- ^ What's in the CPI and what does it actually measure? (theconversation.com)
- ^ non-discretionary (www.abs.gov.au)
- ^ 6.6% (www.abs.gov.au)
- ^ 2.7% (www.abs.gov.au)
- ^ less money to spend (www.smh.com.au)
- ^ $250 cash payments (ministers.treasury.gov.au)
- ^ stagflation (www.smh.com.au)
- ^ Inflation hits 5.1%. How long until mortgage rates climb? (theconversation.com)
- ^ monthly measure (melbourneinstitute.unimelb.edu.au)
- ^ zero (cdn.theconversation.com)
- ^ 9% (tradingeconomics.com)
- ^ aggressively (www.investopedia.com)
- ^ 2.3% (www.abs.gov.au)
Authors: Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University