
Why do bankers behave so badly? They make too much money to ask questions
- Written by: Mark Crosby, Professor, Monash University
Over the past 16 months journalists have been scouring through more than 2,000 Suspicious Activity Reports originally sent by banks to the United States Treasury, before being leaked to Buzzfeed and then passed along to the International Consortium of Investigative Journalists[1].
The reports relate to more than US$2 trillion in transactions over the period from 2000 to 2017. Some of these transactions will already have been investigated, and may be legitimate. In the case of the Australian banks, the regulator AUSTRAC has already asked the US Treasury[2] for some of this information.
There are a number of questions raised by this latest episode of bad behaviour by banks. Firstly, why don’t banks have better controls to stop these kinds of transactions from occurring?
With transactions from tax havens, from shell companies, or to countries under sanction why aren’t banks themselves doing some investigation rather than simply passing information along to the US Treasury?
The short answer is that banks make too much money and it is not in their interest to ask too many questions.
An obvious example are the transactions processed by JP Morgan relating to the 1Malaysia Development Berhad scandal[3] which netted the bank millions of dollars in fees despite the obvious questions the transactions should have raised.
International Consortium of Investigative Journalists.A second question is why do banks consistently seem to behave so badly?
Australia has seen banking scandal after banking scandal over the last 30 years, with the latest detailed in the report of the Hayne Royal Commission[4] in 2019.
Big rewards, less regulation
I believe the reason the banking industry is particularly prone to scandals is because of the amount of cash sloshing through the system, and the fact that in recent years there have been fewer regulations and less policing than is needed.
Deregulation has been the general trend in finance since the mid-1980s, first in the United States and Britain, and then in countries such as Australia.
Australia’s deregulation began with the floating of the exchange rate[5] in 1983 followed by the removal of controls over bank interest rates and bank deposits with the Reserve Bank.
Sure enough, Australia’s first banking scandal was the Swiss loans affair[6] in 1985 in which unsophisticated Australians were encouraged to borrow in a foreign currency oblivious to the risk the Australian dollar might fall forcing them to pay back much more than they borrowed.
Read more: No better than roulette. How foreign exchange trading rips off mum and dad investors[7]
In the United States the Savings and Loan debacle[8] occurred at roughly the same time. A classic example is a large bank in Ohio, Home State, that failed in 1985. Depositors in Home State thought they were safe because their deposits were insured, but deregulation of deposit insurance led to private insurers. The deposit insurance company failed alongside Home State, leaving nothing for insurance payouts.
The next major banking disaster was the Asian financial crisis[9] in 1997. Deregulated banks in countries including Korea and Thailand failed due to large unregulated inflows the systems in these countries couldn’t handle.
No learning from history
A follow-on was the failure of Long Term Capital Management[10], a highly leveraged (borrowed) hedge fund in 1998. The US Treasury engineered a bailout of Long Term Capital Management that was favourable to its shareholders and lenders instead of letting it fail.
There were a number of obvious regulatory problems that led to the crisis. Hedge funds were not required to report their positions in these markets and the risk they were creating or exposed to. They were highly leveraged. Unsophisticated financial markets suffered unmanageable large capital flows.
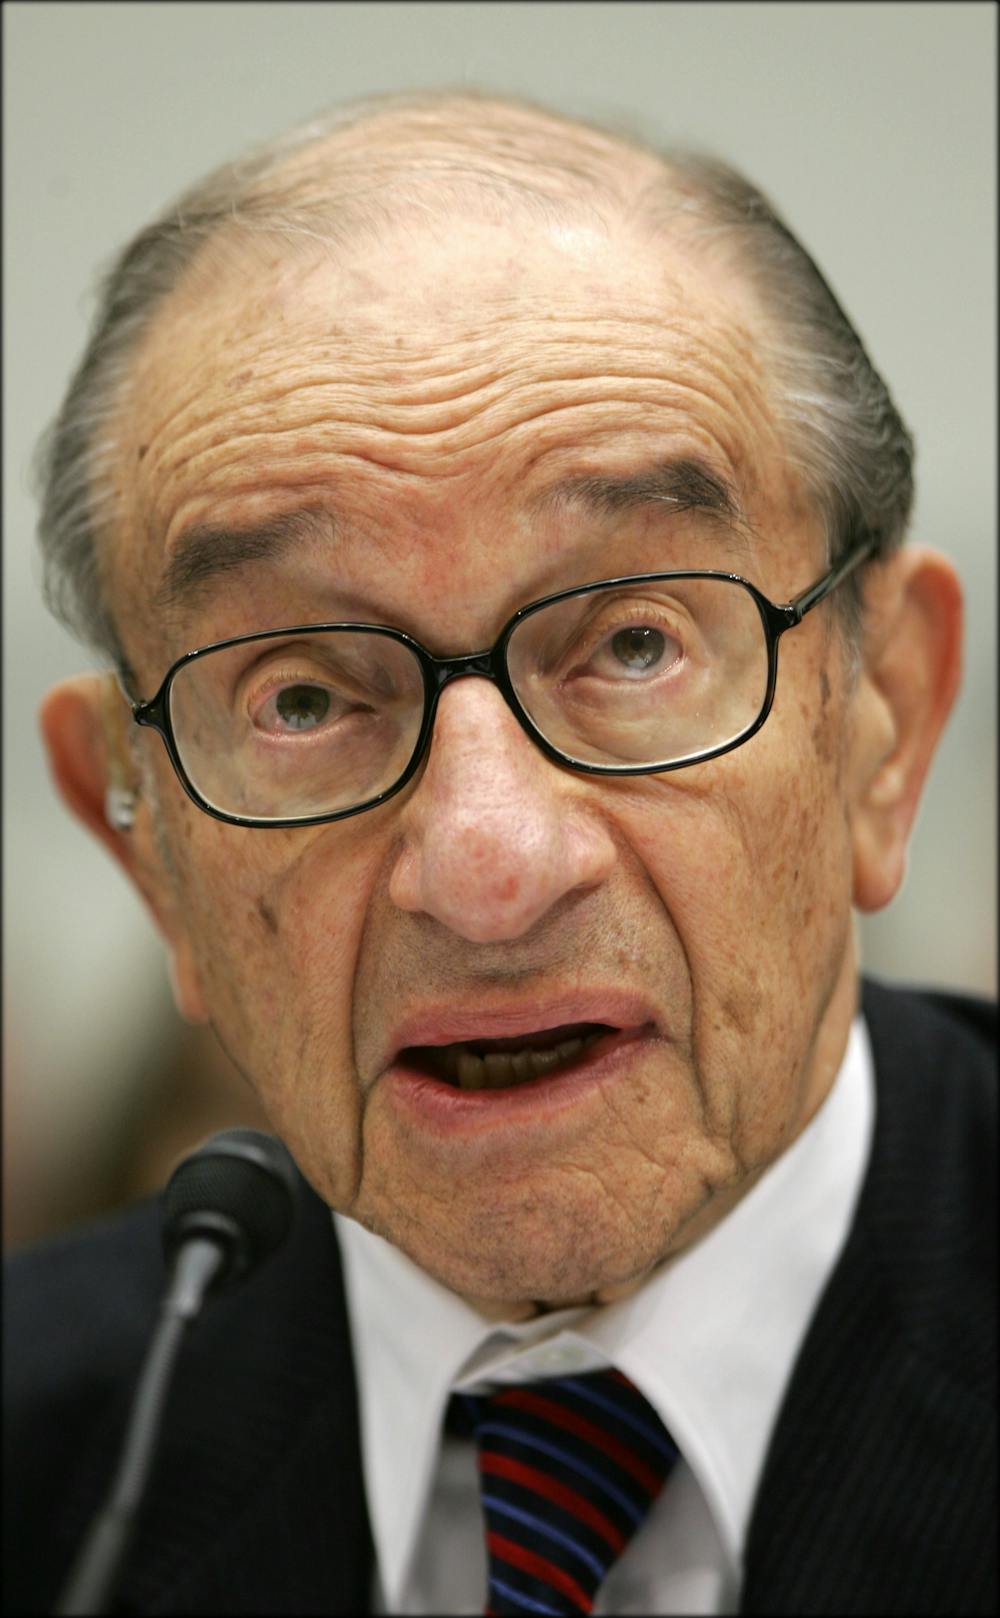 Alan Greenspan was head of the US Federal Reserve but opposed to regulation.
During the crisis the Governor of the US Federal Reserve was Alan Greenspan, a man philosophically opposed to regulation.
He was a follower of the philosophy of Ayn Rand[11], whose view was that the government was incompetent and regulation was unnecessary.
Greenspan noted the contradiction in being a public servant of this mindset, but tried to further deregulate finance wherever and however possible.
Despite the Asian crisis coming close to creating the first global financial meltdown, there was no slowing in deregulation afterwards.
The result was the global financial crisis[12].
Once again, high leverage and opacity were culprits, along with deregulation in derivatives markets and poor design for some market structures.
Even businesses want better regulation
After the global financial crisis, deregulation continued, at times despite the wishes of industries affected. On Monday this week 381 companies signed a letter arguing against[13] a proposal that would remove the need for hedge funds to disclose their stock market holdings. US Treasury Secretary Steve Mnuchin used to work in a hedge fund. He is unlikely to back down.
And this week the first details of the 16-month investigation were released, exposing major issues with transactions by the largest banks in the United States and United Kingdom in particular, but also all four of Australia’s major banks, and Macquarie Bank which was used for more than US$120 million (A$167 million) of suspicious transactions.
Read more: Why credit rating agencies' economic advice shouldn't be trusted[14]
Many won’t be illegal, but the suspicious activity reports suggest that where there is a conflict between profit and ethical decision making, profit usually wins.
I don’t think the reason for this is that all people in finance are unethical, but an industry with such a lot of cash floating around and too little regulation is likely to attract people with questionable ethics.
It needn’t mean a return to the old days
Regulation needn’t mean a reversion to the old “3-6-3” banking days where deposit rates were 3%, lending rates were 6% and the bank manager was on the golf course by 3pm.
But regulation needs to address disclosure issues, leverage, and issues with “sophisticated” products that create a significant risk of blowing up the global financial system.
Reforms should also focus the minds of management and boards on better behaviour. A simple one would be non-payment of bonuses when the organisation is brought into disrepute. It could be structured along the lines of the two strikes[15] rule on remuneration.
Consumers of financial products are at a considerable information disadvantage, and need better protection. Currently consumer protection in the financial services sector lies with the Australian Securities and Investments Commission (ASIC) and with state consumer affairs offices.
Read more: Lunch with bankers. Even they're unimpressed with their new Banking Code of Conduct[16]
In some cases this works, but neither ASIC nor consumer affairs offices are focused exclusively on protecting consumers against abuses in the financial services sector. ASIC is responsible to businesses and finance professionals as well as consumers, and at times these responsibilities conflict.
The codes of conduct we have are voluntary, although industry bodies can seek ASIC approval. The Australian Banking Association code is essentially toothless[17].
Until there is greater regulation in banking and finance we will continue to endure the kinds of bad behaviour we’ve been lumbered with for decades. And we will continue to pay for it too, when things go bad. It’s not enough to rely on banks to get banks to behave well.
References
- ^ International Consortium of Investigative Journalists (www.icij.org)
- ^ asked the US Treasury (www.smh.com.au)
- ^ 1Malaysia Development Berhad scandal (www.theguardian.com)
- ^ Hayne Royal Commission (theconversation.com)
- ^ floating of the exchange rate (www.smh.com.au)
- ^ Swiss loans affair (theconversation.com)
- ^ No better than roulette. How foreign exchange trading rips off mum and dad investors (theconversation.com)
- ^ Savings and Loan debacle (en.wikipedia.org)
- ^ Asian financial crisis (www.investopedia.com)
- ^ Long Term Capital Management (www.managementstudyguide.com)
- ^ Ayn Rand (www.vanityfair.com)
- ^ global financial crisis (www.rba.gov.au)
- ^ arguing against (www.ft.com)
- ^ Why credit rating agencies' economic advice shouldn't be trusted (theconversation.com)
- ^ two strikes (www.afr.com)
- ^ Lunch with bankers. Even they're unimpressed with their new Banking Code of Conduct (theconversation.com)
- ^ essentially toothless (theconversation.com)
Authors: Mark Crosby, Professor, Monash University